How COBRA Insurance Works After Losing Your Job | CafeHealth
COBRA lets you keep the exact same health insurance you had at work for a limited time after you lose your job, but you have to pay the full premium yourself, usually plus a 2% fee. There's no new plan to learn, no new doctors to find, and no waiting period. You just keep what you had. The catch is cost: your employer was probably covering a big chunk of that premium while you worked there, and once you leave, that subsidy disappears. You get to keep the coverage, but you're now writing the whole check.
This matters because a lot of people assume COBRA is automatic or free, and neither is true. You have to actively enroll within a set window, and the price tag can be a shock if you're used to seeing only your payroll deduction. Let's walk through exactly how COBRA continuation coverage works, who qualifies, what it costs, and what happens if deadlines get missed.
What Exactly Is COBRA, and Does It Apply to Your Old Employer?
COBRA stands for the Consolidated Omnibus Budget Reconciliation Act, a federal law passed back in 1985. It gives you the legal right to stay on your former employer's group health plan after certain life events, even though you're no longer an employee. It covers medical, dental, and vision plans, and it also applies to spouses and dependents who were on the plan.
The 20-Employee Rule
COBRA doesn't apply to every employer. Under IRS Code Section 4980B, it only applies to companies with 20 or more employees on more than 50% of its working days in the prior calendar year, counting both full-time and part-time workers (part-timers count as a fraction of a full-time employee). If your old employer had fewer than 20 workers, federal COBRA doesn't apply to you.
That doesn't necessarily mean you're out of luck, though. Several states, including Arizona, have their own continuation laws sometimes called "mini-COBRA" that can require small employers or insurers to offer similar continuation rights. If your employer was small, it's worth asking your HR contact or the Arizona Department of Insurance and Financial Institutions whether a state rule applies to your situation.
Which Plans Qualify
COBRA applies to group health plans, which includes medical, dental, vision, and health flexible spending accounts in some cases. It does not apply to life insurance, disability insurance, or retirement plans. Those end when your employment ends, full stop.
What Counts as a Qualifying Event?
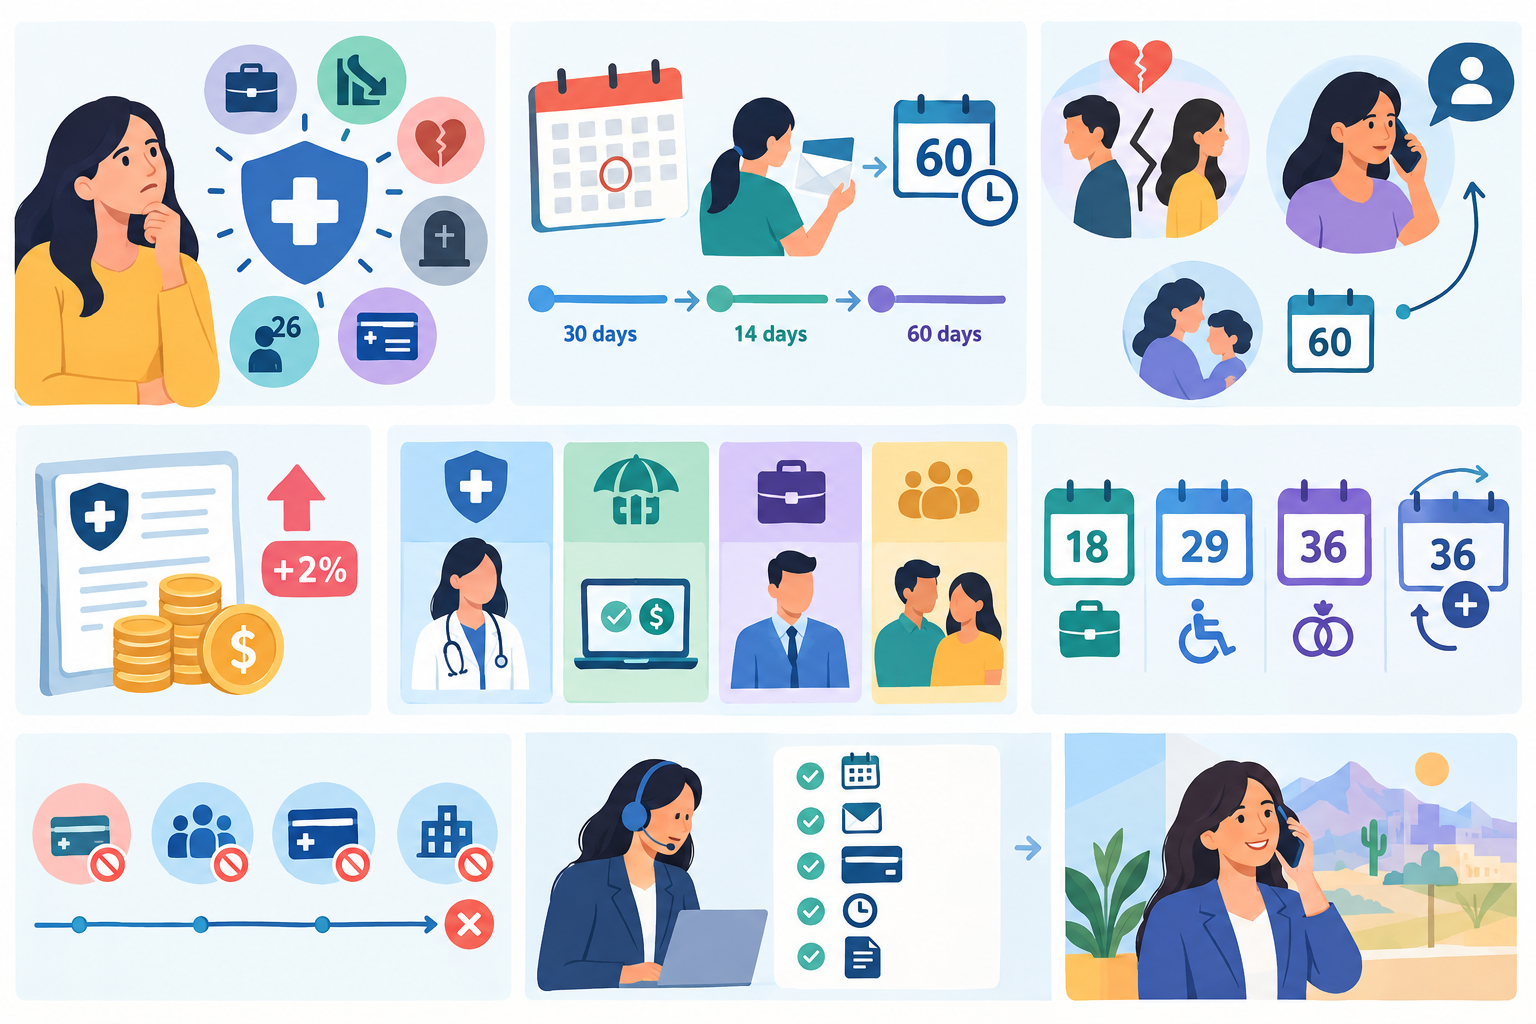
You don't get COBRA just because you feel like keeping your insurance. A specific qualifying event has to happen, and the event determines both who's eligible and how long coverage can last. The most common qualifying events are:
●Voluntary or involuntary termination of employment, for any reason other than "gross misconduct" (more on that below)
●Reduction in hours that causes you to lose eligibility for the health plan, even if you're still employed
●Divorce or legal separation from the covered employee, which affects the spouse's coverage
●Death of the covered employee, which affects the spouse and dependents
●A dependent child aging out of eligibility under the plan's rules, usually around age 26
●The covered employee becoming entitled to Medicare, which can trigger COBRA rights for dependents
Each event type has its own maximum coverage length, which we'll cover later. For now, the key thing to know is that the event has to be reported, either by the employer or by you, within specific timeframes or the whole process stalls.
How Much Time Do You Actually Have to Sign Up?
This is where people get tripped up, because there are actually two separate clocks running, and they belong to two different parties.
Your Former Employer's Notice Deadline
When the qualifying event is something the employer controls, like a layoff or reduction in hours, the employer generally has 30 days to notify the plan administrator. If the employer is also the plan administrator (common with smaller self-administered plans), that same 30-day clock applies before they have to send you the formal election notice. Once notified, the plan administrator has 14 days to send you the COBRA election notice, according to DOL EBSA COBRA guidance. In practice, that means you should hear something within about 44 days of your last day, though it's often faster.
Your Election Deadline
Once you receive that notice, you have 60 days to decide whether to elect COBRA coverage, per the Department of Labor's Employee Benefits Security Administration (EBSA). That 60-day clock starts from whichever is later: the date of the qualifying event or the date you receive the election notice. You don't have to pay anything right when you elect it, but once you do elect, you'll owe retroactive premiums back to the date your old coverage ended, so there's no gap in coverage. If you decide not to elect, you simply let the window close with no obligation.
One important wrinkle: if the qualifying event is a divorce or a dependent losing eligibility, it's on you or the covered employee to notify the plan within 60 days of that event. The employer usually has no way of knowing about a divorce unless you tell them, so this notification duty falls on the employee's side of the fence.
How Much Does COBRA Cost, and How Does It Stack Up Against Other Options?
Here's the part that catches people off guard. Under COBRA rules, your former employer is allowed to charge you up to 102% of the full premium cost, meaning the entire employer-plus-employee share, plus a 2% administrative fee, according to IRS Section 4980B. If you're on a disability extension (more on that below), the allowed charge goes up to 150% of the premium for the extended months.
To put that in perspective, if your health plan costs $650 a month total and your employer was paying $500 of that while you only paid $150, your COBRA bill could jump to around $663 a month once you're covering the whole thing yourself plus the surcharge. That's a real number people need to budget for, not a rounding error.
Before you commit, it's worth comparing your options side by side:
●COBRA: Keeps your exact same plan, doctors, and deductible progress, but usually the most expensive monthly option since there's no employer subsidy
●ACA Marketplace plan: Losing job-based coverage is a qualifying life event that opens a 60-day Special Enrollment Period on Healthcare.gov, and depending on your income, you may qualify for premium tax credits that make it cheaper than COBRA
●A new employer's plan: If you land a new job quickly, enrolling there is typically your cheapest and fastest option, since new hires generally get a similar special enrollment window
●Spouse's employer plan: Losing coverage also qualifies you for a special enrollment window on a spouse's plan, often within 30 days of the loss
There's no universally right answer here. If you're mid-treatment with a specific doctor or deep into a deductible, COBRA's continuity can be worth the extra cost. If budget is the main concern, it's worth running the numbers on a Marketplace plan before defaulting to COBRA.
How Long Does COBRA Coverage Actually Last?
The length of your COBRA eligibility depends entirely on which qualifying event triggered it, according to the DOL's publication \"An Employee's Guide to Health Benefits Under COBRA.\"
●18 months is the standard maximum for termination of employment or reduction in hours
●29 months is available if the Social Security Administration determines you were disabled at any point during the first 60 days of COBRA coverage, this extension covers the disabled individual and family members on the plan
●36 months applies for other qualifying events like divorce, death of the covered employee, or a dependent aging out of eligibility
●Second qualifying events can extend an 18-month period up to 36 months total if, for example, someone already on COBRA due to a layoff later divorces the covered employee
Coverage can end earlier than the max if you stop paying premiums, become covered under another group plan, become entitled to Medicare, or the employer stops offering group health coverage altogether. It's worth marking your calendar for these dates, since there's no automatic renewal or grace period once the maximum runs out.
Why Do So Many Employers Hand COBRA Off to a TPA?
If you're reading this as an HR person rather than someone who just lost coverage, here's the part that should get your attention: COBRA administration is full of hard deadlines, and missing even one can expose your company to real liability. The IRS can impose an excise tax of $100 per day per affected beneficiary (up to $200 per family) for COBRA violations, and the DOL can impose separate penalties of up to $110 per day for notice failures. That adds up fast if a notice goes out late or gets lost in someone's inbox.
A Third Party Administrator (TPA) takes that burden off your plate by handling the whole lifecycle:
1.Tracking qualifying events as they happen across your workforce
2.Sending compliant election notices within the required timeframes
3.Collecting premium payments directly from former employees
4.Managing the 18/29/36-month timelines and second qualifying events
5.Keeping documentation ready in case of a DOL audit or employee dispute
For employers around the Phoenix area, working with a local TPA also means someone who understands Arizona's specific rules alongside the federal ones, and who can actually pick up the phone when a former employee calls confused about their bill. If you want to stop tracking these deadlines on a spreadsheet, take a look at CafeHealth's COBRA administration services in Phoenix to see how the handoff works.
Frequently Asked Questions
How long do I have to sign up for COBRA after losing my job?
You generally get 60 days from whichever is later, the date you lost coverage or the date you receive your election notice, according to DOL EBSA guidance. Don't wait until the last week, since paperwork can take time to process.
How much does COBRA insurance cost per month?
You can be charged up to 102% of the total premium your employer was paying on your behalf, meaning both your old payroll deduction and whatever your employer was contributing, plus a small administrative fee. The exact number depends on your old plan, so ask your former HR department for the specific premium amount.
Can I get COBRA if I was fired instead of laid off?
In most cases, yes. COBRA covers termination for almost any reason, including being fired. The one exception is termination for \"gross misconduct,\" a narrow legal standard that goes beyond normal performance issues, like theft or serious policy violations. Most terminations don't meet that bar.
How long does COBRA coverage last?
The standard max is 18 months for job loss or reduced hours. It can stretch to 29 months with a Social Security disability determination, or up to 36 months for events like divorce or a dependent aging off the plan.
What happens if my employer doesn't send me a COBRA notice on time?
Late or missing notices are a real compliance problem for the employer, not something you just have to accept. The IRS and DOL can both levy penalties against employers for notice failures, sometimes $100 to $110 per day per affected person. If you never got a notice, contact the plan administrator in writing and consider reaching out to the DOL's regional EBSA office for guidance.
Is COBRA the same thing as my old insurance, or a different plan?
It's the exact same plan, same network, same deductible you already paid toward this year. COBRA doesn't create new coverage, it just extends your right to stay on the plan you already had, which is the main reason people choose it over shopping for something new.
If any of this feels like a lot to track, whether you're an employee trying to figure out your next move or an HR team trying to stay compliant, it helps to talk it through with someone who does this every day. Grab a free consultation with Shannon and get straight answers for your specific situation.
How long do I have to sign up for COBRA after losing my job?
You generally get 60 days from whichever is later, the date you lost coverage or the date you receive your election notice, according to DOL EBSA guidance. Don't wait until the last week, since paperwork can take time to process.
How much does COBRA insurance cost per month?
You can be charged up to 102% of the total premium your employer was paying on your behalf, meaning both your old payroll deduction and whatever your employer was contributing, plus a small administrative fee. The exact number depends on your old plan, so ask your former HR department for the specific premium amount.
Can I get COBRA if I was fired instead of laid off?
In most cases, yes. COBRA covers termination for almost any reason, including being fired. The one exception is termination for \"gross misconduct,\" a narrow legal standard that goes beyond normal performance issues, like theft or serious policy violations. Most terminations don't meet that bar.
How long does COBRA coverage last?
The standard max is 18 months for job loss or reduced hours. It can stretch to 29 months with a Social Security disability determination, or up to 36 months for events like divorce or a dependent aging off the plan.
What happens if my employer doesn't send me a COBRA notice on time?
Late or missing notices are a real compliance problem for the employer, not something you just have to accept. The IRS and DOL can both levy penalties against employers for notice failures, sometimes $100 to $110 per day per affected person. If you never got a notice, contact the plan administrator in writing and consider reaching out to the DOL's regional EBSA office for guidance.
Is COBRA the same thing as my old insurance, or a different plan?
It's the exact same plan, same network, same deductible you already paid toward this year. COBRA doesn't create new coverage, it just extends your right to stay on the plan you already had, which is the main reason people choose it over shopping for something new.