Lifestyle Spending Account (LSA) Rules & Taxes | CafeHealth
A Lifestyle Spending Account (LSA) is money your employer sets aside for you to spend on wellness-related stuff they choose to cover, like gym memberships, therapy copays, or even pet food, and unlike an FSA or HSA, it's not a tax-advantaged account under the IRS rulebook. That means the employer funds it, decides what counts as an eligible expense, and in most setups, the money is treated as taxable income when you use it. No special tax code section governs LSAs the way IRC Section 125 governs FSAs or Section 223 governs HSAs, which is exactly why employers have so much freedom to design them however they want.
If you're an HR person trying to figure out whether an LSA makes sense for your benefits lineup, or an employee staring at a new line item in your benefits portal wondering what you're allowed to spend it on, this guide walks through the whole thing. We'll cover the tax treatment, the expense categories employers typically allow, how contribution amounts get decided, what happens to unused money, and how a third-party administrator actually handles the day-to-day claims and compliance side of it.
What exactly is a Lifestyle Spending Account?
Think of an LSA as a flexible perk fund rather than a formal insurance benefit. Your employer puts a set amount of money into an account tied to your name, and you submit receipts (or use a benefits card) to get reimbursed for things on an approved list. The employer builds that list, not the IRS, which is the biggest structural difference from an FSA, HSA, or HRA.
How it's different from FSA, HSA, and HRA
Traditional pretax accounts like Flexible Spending Accounts (FSAs), Health Savings Accounts (HSAs), and Health Reimbursement Arrangements (HRAs) all exist because Congress wrote specific tax code sections for them. That's why they come with IRS-set contribution caps, eligibility rules tied to high-deductible health plans, and strict lists of qualified medical expenses defined in IRS Publication 502. An LSA doesn't have any of that baked-in structure. Here's the quick comparison:
●FSA: Pretax payroll contributions, IRS contribution limit ($3,300 for 2025 per IRS guidance), use-it-or-lose-it with limited carryover or grace period options, must be used for IRS-qualified medical expenses.
●HSA: Pretax or tax-deductible contributions, requires enrollment in a qualifying high-deductible health plan, IRS contribution limit ($4,300 individual / $8,550 family for 2025), funds roll over indefinitely and the account is owned by the employee.
●HRA: Employer-funded only, tax-free to the employee when used for qualified medical expenses, rules vary by HRA type (QSEHRA, ICHRA, excepted benefit HRA), employer sets contribution amounts within IRS guardrails.
●LSA: Employer-funded, generally taxable to the employee, no IRS contribution limit, employer defines eligible expenses, and plan design (not the tax code) determines rollover and forfeiture rules.
That last point is worth sitting with for a second. Because an LSA isn't built on a specific IRC section, employers get to be creative with what it covers, which is exactly why LSAs have become popular as a catch-all wellness perk that sits alongside more traditional benefits.
Is money from a Lifestyle Spending Account taxable?
In almost every case, yes. Since an LSA doesn't operate under Section 125 or Section 223, the IRS doesn't give it the tax-free treatment those accounts enjoy. Per IRS Publication 15-B (Employer's Tax Guide to Fringe Benefits), cash and cash-equivalent fringe benefits, which is essentially what an LSA reimbursement is, get added to an employee's taxable wages. That means LSA reimbursements are typically subject to:
●Federal income tax withholding
●Social Security tax (6.2%)
●Medicare tax (1.45%)
These withholding rules come straight from IRS Publication 15 (Circular E, Employer's Tax Guide), which governs how employers handle payroll taxes on wages and taxable fringe benefits. For Phoenix-based employers specifically, the Arizona Department of Revenue also treats taxable fringe benefits as part of gross wages subject to state withholding, so LSA reimbursements need to run through payroll correctly at the state level too, not just federal.
This is where a lot of employers trip up. If an LSA reimbursement gets paid outside of payroll, like a direct deposit from a benefits card provider with no tax withholding applied, that's a compliance gap waiting to surface during an audit. The reimbursement still counts as income to the employee, whether or not taxes got withheld correctly in the moment. That's a big reason employers lean on a dedicated administrator to make sure LSA payouts get reported through payroll with the right withholding applied every pay cycle, not reconciled after the fact.
What can employees actually use LSA funds for?
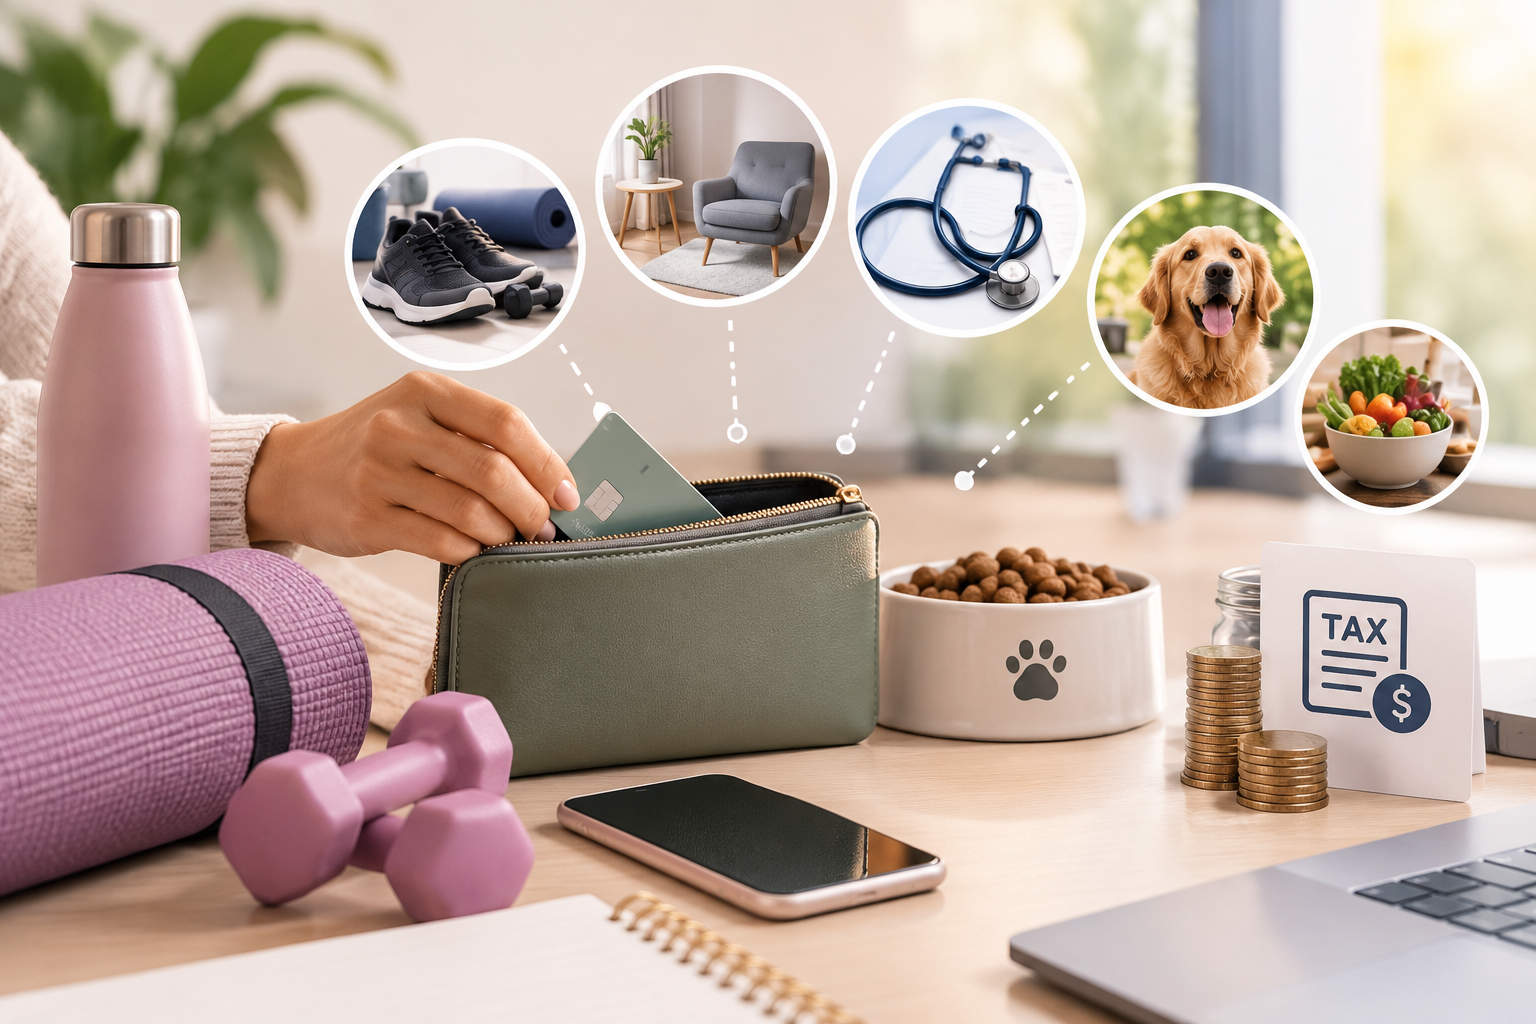
This is the fun part, and also the part where employer customization really shines. Because there's no IRS list dictating what counts as an eligible LSA expense, employers get to build a menu that matches their culture and their workforce's actual needs. Common categories include:
●Fitness and movement: gym memberships, home workout equipment, fitness classes, personal training
●Mental health and wellness: therapy copays not covered elsewhere, meditation app subscriptions, life coaching
●Financial wellness: financial planning sessions, student loan payments, credit counseling
●Family and caregiving support: childcare costs, elder care assistance, adoption expenses
●Pet care: veterinary bills, pet insurance premiums
●General lifestyle: travel, hobby classes, home office equipment, even subscription services
Some employers keep it narrow and focused purely on physical and mental wellness. Others open it up wide as a flexible perk stipend that functions more like a culture-building tool than a health benefit. Both approaches are valid, and both still fall under the same taxable treatment described above, since the IRS doesn't distinguish between a gym membership and a Netflix subscription when it comes to fringe benefit taxation. What matters for compliance is that the employer writes the eligible expense list clearly in the plan document and applies it consistently across employees, so nobody can claim favoritism or discrimination in how reimbursements get approved.
How do employers decide contribution amounts and eligibility rules?
Since there's no IRS cap on LSA contributions, this part is entirely up to the employer's budget and goals. Most employers land somewhere between a few hundred and a couple thousand dollars a year per employee, though there's genuinely no ceiling or floor set by federal rules. A few design questions come up again and again when employers are building out an LSA:
1.Who's eligible? Full-time only, or full-time and part-time? Day-one eligibility or after a waiting period tied to other benefits?
2.How much does each employee get? A flat dollar amount for everyone, or tiered amounts based on role, tenure, or location?
3.How does someone submit a claim? Receipt-based reimbursement through a portal, a dedicated benefits debit card, or both?
4.What documentation is required? Most employers still require some form of substantiation, like a receipt showing the expense matches an eligible category, even though the IRS doesn't mandate it for a taxable benefit.
5.Does the plan touch ERISA? According to Department of Labor (DOL) guidance on ERISA-covered welfare benefit plans, an LSA that's purely a cash wellness perk generally sits outside ERISA, but if the plan starts covering things that look like group health benefits, such as reimbursing medical copays, it can trigger ERISA obligations depending on how it's structured. This is a nuance worth reviewing with your administrator or benefits counsel before finalizing the eligible expense list.
Because employers control every one of these levers, two companies in the same industry can end up with wildly different LSA designs. That flexibility is the whole appeal, but it also means there's no out-of-the-box template to copy. Getting the plan document, the eligible expense list, and the payroll tax process aligned up front saves a lot of headaches later.
Do unused LSA funds roll over to the next year?
It depends entirely on what the employer decides, because again, there's no IRS rule forcing a use-it-or-lose-it structure or a mandatory rollover like you'd see with an FSA. Employers typically pick one of three approaches:
●Forfeiture at year-end: Unused funds simply go away when the plan year closes, similar to how FSAs traditionally worked before carryover provisions became common.
●Full rollover: Unused balances carry into the next plan year, functioning more like a savings-style benefit.
●Partial rollover or vesting schedule: A portion carries over, or funds vest based on tenure, which some employers use as a retention tool.
None of these choices creates a compliance problem on its own, since the rollover question is a plan design decision rather than a tax code requirement. What does matter is writing the rule down clearly in the plan document and communicating it to employees before the plan year starts, so nobody is surprised in December when their balance disappears. If your organization wants the LSA to double as a retention or loyalty tool, a vesting schedule tied to tenure can be a smart lever to pull. If you want it to feel like a simple annual perk, forfeiture keeps the budgeting predictable year over year.
How does CafeHealth actually administer an LSA day to day?
Running an LSA well comes down to three things working together: clean claims processing, consistent substantiation, and accurate payroll tax reporting. At CafeHealth, that looks like setting up the eligible expense categories your organization chooses, processing employee submissions against those rules, and making sure every reimbursement flows through payroll with the correct federal and state withholding applied, including Arizona-specific state withholding requirements for Phoenix-based employers. We also help employers think through the ERISA question up front, so the plan design doesn't accidentally create obligations nobody intended.
For employees, that means a straightforward way to submit a receipt or swipe a benefits card, see the claim get reviewed against the plan's rules, and get reimbursed without a lot of back-and-forth. For employers, it means not having to manually track eligible categories, reconcile payroll tax withholding, or chase down documentation every pay period. If you're an employer in the Phoenix area exploring whether an LSA fits your benefits strategy, our team handles the LSA administration services in Phoenix from plan design through ongoing claims support, so you're not building this from scratch on your own.
What's the honest bottom line here?
An LSA is a genuinely flexible tool, and that flexibility is both its biggest strength and the thing that requires the most upfront planning. Unlike an HSA or FSA, there's no IRS rulebook telling you exactly how to build it, which means the employer has to make every decision, from contribution amounts to eligible expenses to rollover rules, and then administer it consistently. Get the tax withholding right, write the plan rules clearly, and decide early whether unused funds roll over or disappear. Do that, and an LSA becomes one of the more employee-loved perks in a benefits package, precisely because it can flex around real life instead of being boxed in by what counts as a qualified medical expense.
If you're weighing an LSA against other options, or trying to figure out how it fits alongside an existing HSA, FSA, or ICHRA offering, talking it through with someone who administers these day in and day out tends to save a lot of trial and error. You can book a free consultation with Shannon to walk through what an LSA could look like for your team, no pressure, just a straightforward conversation about what fits.
Quick Questions People Actually Ask About LSAs
What is a lifestyle spending account (LSA)?
It's a pot of money your employer funds and lets you spend on wellness-ish stuff they've approved, like gym memberships, therapy, or financial coaching. It's not a government-defined account like an HSA or FSA, so the employer decides the rules.
Is money from a lifestyle spending account taxable?
Usually, yes. Since LSAs aren't set up under Section 125 or 223 of the tax code, the IRS generally treats reimbursements as taxable wages, meaning income tax, Social Security, and Medicare all apply, per IRS Publication 15-B.
What can I use my LSA funds for?
Whatever your employer put on the approved list. Common stuff includes gym memberships, therapy copays, financial planning, childcare costs, and even pet care. Check your plan document because every employer's list looks different.
How is an LSA different from an HSA or FSA?
HSAs and FSAs are pretax accounts with IRS-set contribution limits and specific rules about what counts as a qualified medical expense. LSAs have none of that structure, there's no federal contribution cap, the money is generally taxable, and the employer picks what's eligible.
Do unused LSA funds roll over to the next year?
Only if your employer's plan says so. Some plans forfeit unused balances at year-end, some roll everything over, and some vest a portion based on tenure. It's entirely a plan design choice, not an IRS rule.
Can my employer offer an LSA alongside my HSA or FSA?
Yes, and a lot of employers do exactly that. An LSA can run right alongside an HSA, FSA, or HRA since it's not governed by the same tax rules, so there's no conflict with contribution limits or eligibility requirements between the two.