How Does COBRA Continuation Coverage Work? | CafeHealth
So, How Does COBRA Continuation Coverage Actually Work?
COBRA continuation coverage works by letting you keep the exact same group health plan you had through your job, for a limited stretch of time, after something called a \"qualifying event\" knocks you off that plan — think getting laid off, your hours getting cut, or a divorce that drops you from your spouse's coverage. The catch is that you now pay the full premium yourself, including the part your employer used to cover, plus the plan is allowed to tack on a small administrative fee. It's not new insurance. It's the same doctors, same network, same deductible you already met this year — just without your employer chipping in anymore.
This isn't some optional perk employers dream up. It's federal law. The Consolidated Omnibus Budget Reconciliation Act of 1985, known as COBRA, amended ERISA, the Internal Revenue Code, and the Public Health Service Act to require most employer-sponsored group health plans to offer this bridge coverage. The U.S. Department of Labor's Employee Benefits Security Administration (EBSA) oversees the rules on the private-sector side, and the IRS enforces the tax code provisions under IRC Section 4980B. We'll walk through who qualifies, how long it lasts, what it actually costs, and the deadlines that trip people up most often.
What Exactly Is COBRA, and Who Has to Offer It?
COBRA applies to group health plans sponsored by private-sector employers with 20 or more employees on more than 50% of their typical business days in the prior calendar year, according to IRC Section 4980B(d) and DOL guidance. That count includes full-time and part-time workers, with part-timers counted proportionally. State and local government plans fall under a similar rule in the Public Health Service Act. Smaller employers aren't off the hook entirely — most states have their own \"mini-COBRA\" laws that require continuation coverage for smaller group plans, though the rules and timelines vary by state.
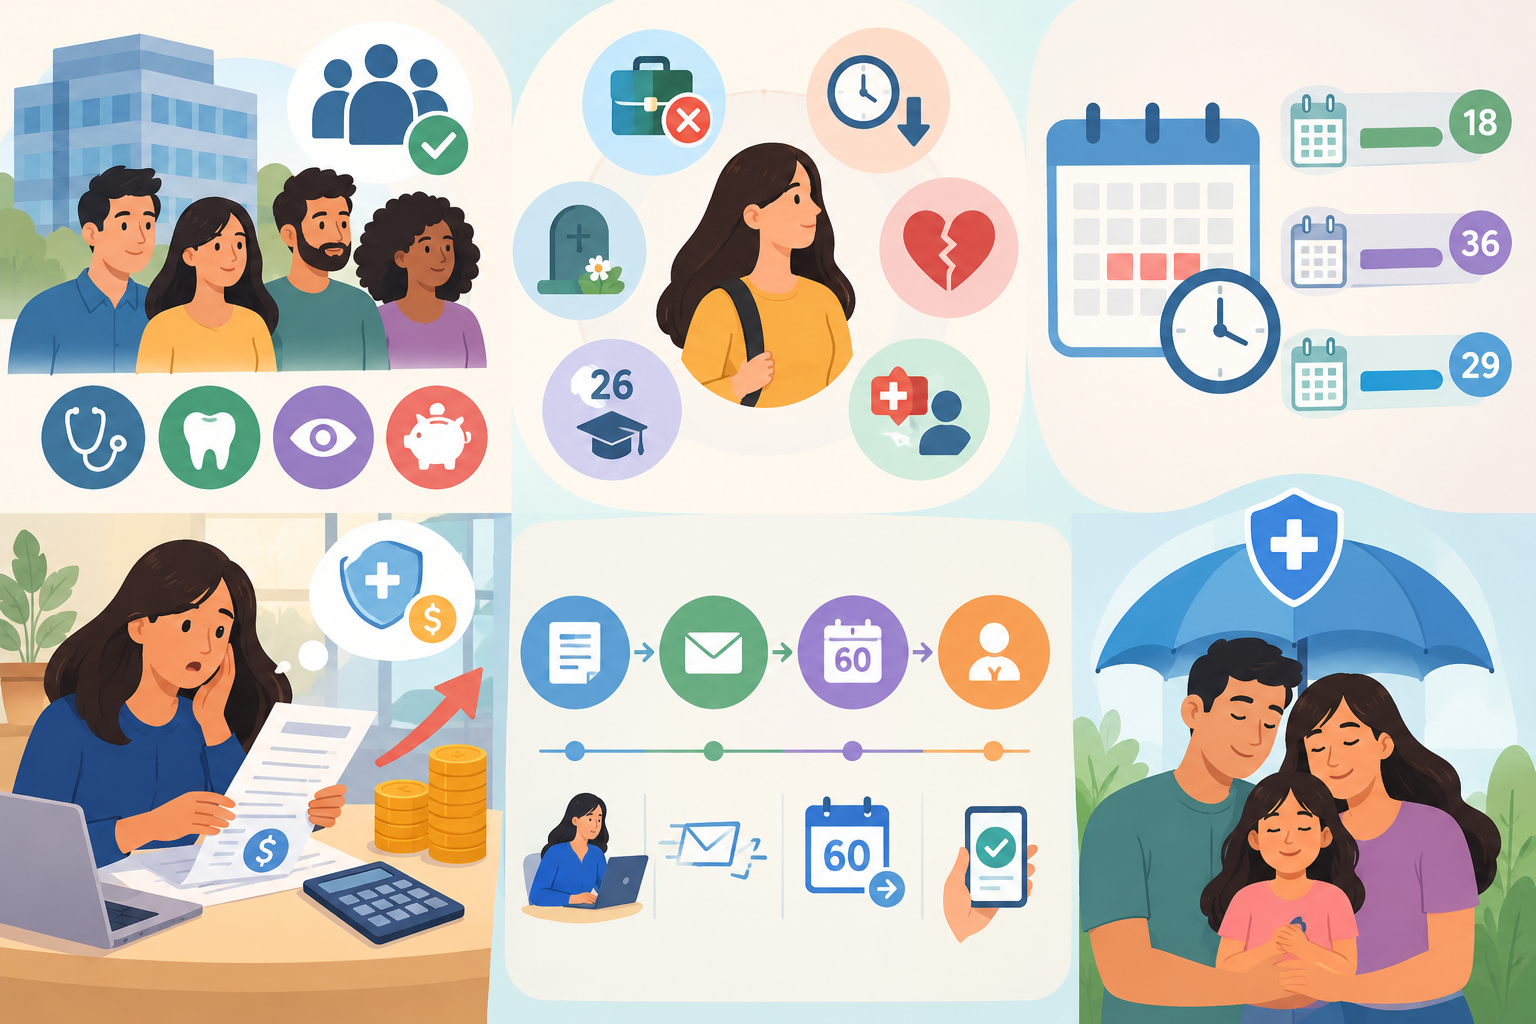
COBRA covers more than just medical insurance. It extends to dental, vision, and health flexible spending accounts (FSAs) if those were part of the group health plan. It does not cover life insurance, disability insurance, or retirement plans — those fall outside COBRA's scope entirely. The people eligible to elect it are called \"qualified beneficiaries,\" which includes the employee, their spouse, and any dependent children who were covered under the plan the day before the qualifying event happened.
What Counts as a Qualifying Event?
A \"qualifying event\" is the legal term for the specific life change that triggers COBRA rights. Not every way you lose coverage counts, and the event determines both who's eligible and how long their coverage can last. The most common qualifying events are:
●Voluntary or involuntary termination of employment — for any reason other than \"gross misconduct,\" which is a narrow exception plans rarely use successfully
●Reduction in hours that causes someone to drop below the threshold for plan eligibility, even if they're still employed
●Divorce or legal separation from the covered employee
●Death of the covered employee
●A dependent child aging out, typically at 26, or otherwise losing dependent status under the plan's terms
●The covered employee becoming entitled to Medicare, which can trigger COBRA rights for their dependents
One detail people miss: quitting your job on purpose still counts as a qualifying event. COBRA doesn't care whether you were fired, laid off, or walked out on your own — as long as it's not gross misconduct, you're eligible to elect continuation coverage.
How Long Does COBRA Coverage Actually Last?
This is where a lot of confusion comes from, because the answer depends entirely on which qualifying event triggered it. Per DOL's EBSA guidance and the regulations at 29 CFR 2590.606:
●18 months for termination of employment or reduction in hours — this is the most common scenario
●36 months for divorce, legal separation, death of the employee, Medicare entitlement of the employee, or a dependent losing eligible status
●Up to 29 months if the Social Security Administration determines the qualified beneficiary was disabled at any point during the first 60 days of COBRA coverage — this extends the standard 18-month period by an additional 11 months, but the disability determination has to be reported to the plan within 60 days of the SSA's ruling and before the original 18 months runs out
Coverage can also end early if the employer stops offering group health coverage altogether, the beneficiary becomes covered under another group plan without a pre-existing condition exclusion, or premiums simply aren't paid on time. It's worth noting that COBRA is a maximum, not a guarantee — if your former employer shuts down its health plan entirely, your COBRA coverage ends with it.
Who Pays for COBRA, and Why Does It Feel So Expensive?
Here's the part that catches most people off guard: when you were employed, your employer was almost certainly covering a chunk of your premium. The national average, according to KFF's annual Employer Health Benefits Survey, has employers covering roughly 83% of premium costs for single coverage and about 73% for family coverage. Once you're on COBRA, that employer contribution disappears, and you're responsible for the entire premium — both your old share and the part your employer used to pay.
The 102% Rule
On top of the full premium, plans are allowed to charge an administrative fee of up to 2%, bringing your total cost to as much as 102% of the plan's total premium, per IRC Section 4980B(f)(4). During the 11-month disability extension period (months 19 through 29), that administrative fee cap jumps to 150% of premium, reflecting the added cost of managing that extended coverage window.
This combination — losing the employer subsidy plus the admin fee — is exactly why COBRA premiums often shock people. A plan that cost you $150 a month as a paycheck deduction might suddenly cost $650 or more under COBRA, depending on your employer's contribution level and plan tier.
What's the Actual Timeline for Electing and Paying for COBRA?
The deadlines matter a lot here, and missing one can permanently cost you the right to elect coverage. Here's how the clock typically runs, based on DOL's COBRA Continuation Coverage FAQs:
1.Plan administrators must send a general notice explaining COBRA rights within 90 days of someone's coverage starting under the plan
2.When a qualifying event happens, the employer (if it's also the plan administrator) generally has 44 days total to send the election notice — 30 days to notify the plan, then 14 more for the plan to notify the qualified beneficiary, though many employers handle this as one combined 44-day window
3.For divorce, legal separation, a dependent aging out, or a disability determination, the employee or beneficiary has to notify the plan within 60 days of the event — the employer usually won't know about these events on its own
4.Once the election notice goes out, qualified beneficiaries get a 60-day election period to decide whether to elect COBRA, measured from the later of the date coverage was lost or the date the notice was sent
5.After electing, there's a 45-day grace period to make the first premium payment, which usually has to cover retroactive coverage back to the date the old coverage ended
6.After that, monthly payments typically come with a 30-day grace period unless the plan document allows more time
That 60-day election window is a commonly cited figure straight from DOL's COBRA guidance, and it trips up a lot of people who assume they've lost their shot the moment their old coverage ends. You genuinely have two months to decide, and you can even wait until close to the deadline and still get retroactive coverage back to day one — which matters if you need to use your plan in the meantime and decide to pay for it later.
What Happens If an Employer Gets COBRA Wrong?
This is the part that should get HR's attention. COBRA compliance isn't a \"best effort\" situation — it comes with real financial teeth. Under IRC Section 4980B, the IRS can impose an excise tax of $100 per day per qualified beneficiary (up to $200 per day per family) for each day a plan is out of compliance, and separately, ERISA allows penalties of up to $110 per day for failing to provide required notices, enforced by the DOL. There's also exposure to beneficiary lawsuits if someone loses coverage, racks up medical bills, and can show the employer botched or missed a notice.
The most common mistakes aren't exotic — they're things like sending the election notice late, using an outdated notice template that's missing required language, miscalculating the premium, or simply losing track of a qualifying event because HR and payroll systems don't talk to each other. Divorce and dependent-aging-out events are particularly easy to miss since the employer often isn't automatically notified.
Should Employers Handle COBRA In-House or Outsource It?
Plenty of smaller employers try to run COBRA themselves, and for a company with just a handful of qualifying events a year, it can feel manageable at first. But the administrative lift adds up fast: tracking deadlines across multiple qualifying event types, generating compliant notices, calculating premiums correctly (including that 102% math), processing payments, handling the disability extension paperwork, and keeping records that would hold up if the DOL or a terminated employee's attorney ever asks questions.
A dedicated COBRA TPA takes that entire workflow off an employer's plate. At CafeHealth, we handle the notice generation, deadline tracking, premium billing, and payment processing so HR teams aren't trying to remember whether a specific divorce notification landed inside the 60-day window. If you want to see exactly how that works for your organization, take a look at our COBRA administration services page for the specifics on how we structure it.
Here's a quick side-by-side of what each approach typically involves:
●In-house administration: requires dedicated staff time, up-to-date knowledge of changing IRS/DOL rules, internal systems to track every qualifying event and deadline, and full liability sitting with the employer if something slips
●Outsourced TPA administration: notices, timelines, and premium calculations are handled by a team that does this daily, records are kept audit-ready, and the employer's compliance risk drops significantly without adding headcount
For employers juggling other benefits like FSAs, HSAs, HRAs, or ICHRA alongside COBRA, there's also real value in having one administrator coordinate all of it, so qualifying events and eligibility changes don't fall through the cracks between systems.
If you're an HR leader weighing in-house versus outsourced COBRA, or an employee trying to figure out your own coverage options after a layoff or divorce, it helps to just talk it through with someone who does this every day. You can book a free consultation with Shannon and get straight answers about your specific situation, no sales pitch required.
Quick Questions People Actually Ask About COBRA
How long does COBRA coverage last after I lose my job?
If you lost your job or had your hours cut, you typically get 18 months of COBRA coverage. If you later get a Social Security disability determination within the first 60 days of that coverage, you can extend it to 29 months total. Other events, like divorce or a dependent aging out, come with a longer 36-month window instead.
How much does COBRA insurance cost per month?
It varies a lot by plan and employer, but the rule is that you pay up to 102% of the full group premium — your old share plus whatever your employer used to kick in, plus a 2% admin fee. Since employers often cover 70-80% of premiums according to KFF's Employer Health Benefits Survey, your monthly cost can jump dramatically compared to what came out of your paycheck.
What counts as a qualifying event for COBRA?
The big ones are losing your job (quit or fired, as long as it's not gross misconduct), getting your hours reduced below plan eligibility, divorce or legal separation, the covered employee's death, a dependent child aging out at 26, or the employee becoming entitled to Medicare. Each one has its own rules for who's eligible and how long coverage lasts.
Can I get COBRA if I quit my job voluntarily?
Yes. COBRA doesn't distinguish between quitting and getting laid off or fired, as long as you weren't terminated for gross misconduct. Voluntarily leaving your job still counts as a qualifying event and still gives you the right to elect continuation coverage.
What happens if I miss the COBRA election deadline?
You generally lose your right to elect coverage. The election period is 60 days from the later of your coverage end date or the date your election notice was sent, and once that window closes, plans aren't required to reopen it. That's why it's worth deciding early even if you don't plan to pay right away — you can elect now and still have 45 days to make your first payment.
Does COBRA cover dental and vision, or just medical insurance?
If dental or vision were part of your employer's group health plan, COBRA covers those too. It does not extend to life insurance, disability coverage, or retirement benefits, since those aren't considered part of the group health plan under COBRA's definition.