How Does ICHRA Work for Employers? | CafeHealth
What is Individual Coverage HRA (ICHRA)?
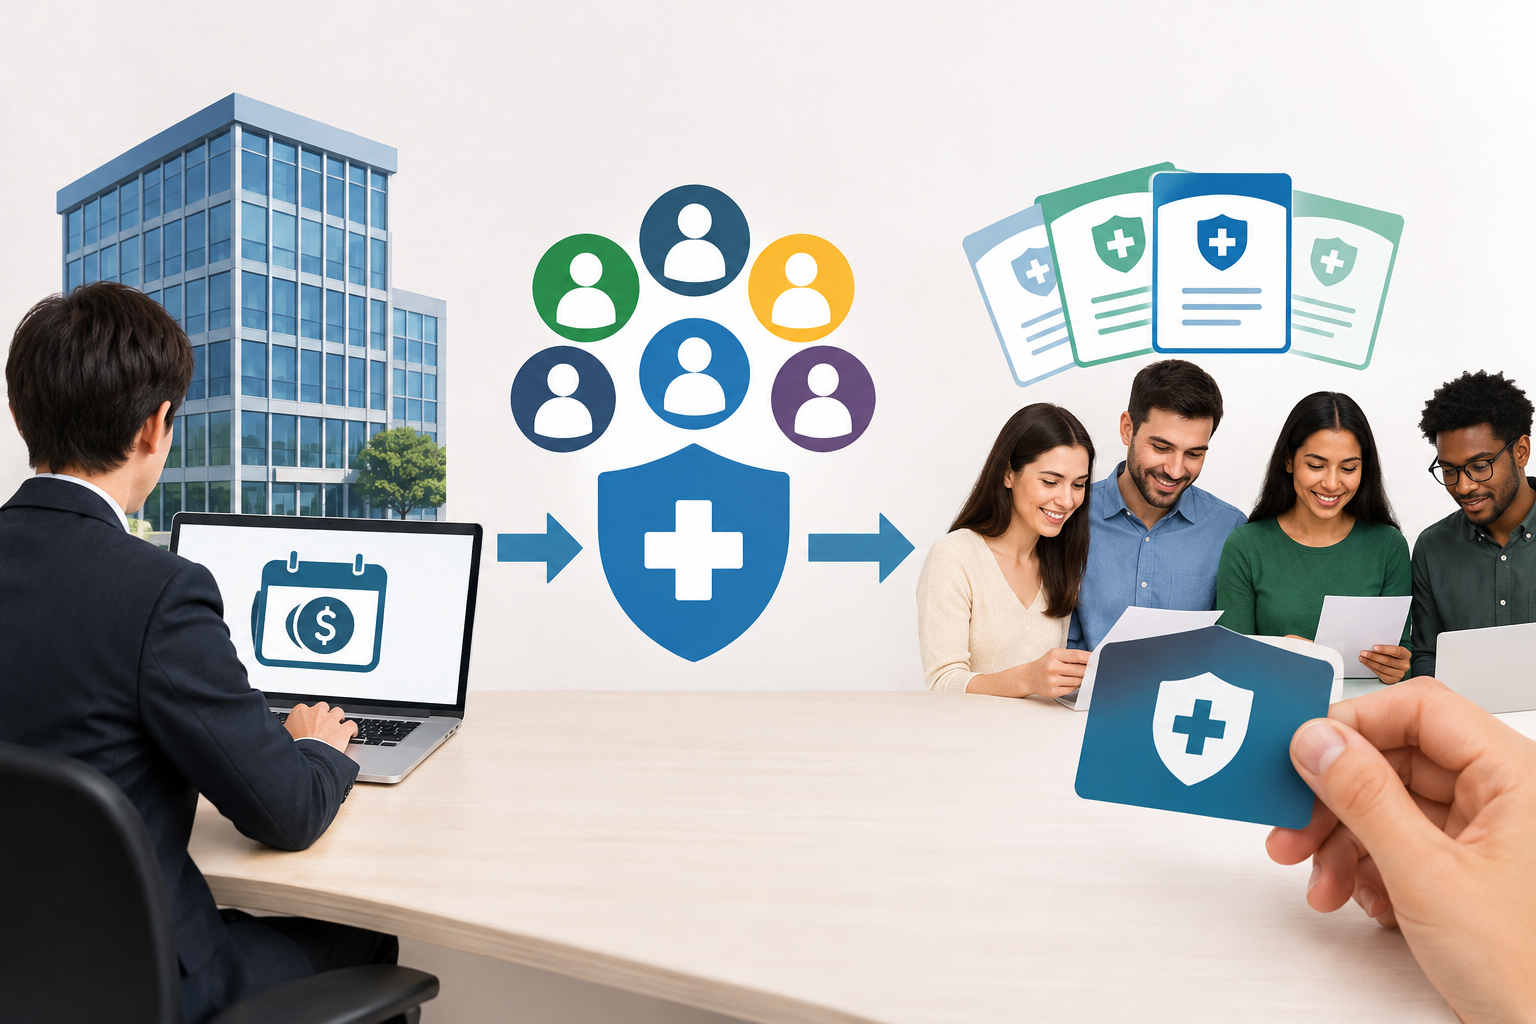
Here's the short version: an ICHRA (Individual Coverage Health Reimbursement Arrangement) works by having your company set aside a fixed dollar amount each month for each employee, and employees use that money to buy their own health insurance on the individual market instead of enrolling in a plan you picked for them. You decide the amount. They pick the plan. You reimburse them, tax-free, once they show proof of coverage. No group plan, no annual renewal negotiation with a carrier, no one-size-fits-all deductible that half your staff complains about.
That's the whole concept in a nutshell, but the details matter a lot if you're actually going to run one. Who counts as eligible? How much do you have to contribute to stay compliant with the ACA employer mandate? What happens to COBRA? This guide walks through all of it, section by section, the way you'd want someone to explain it to you before you sign anything.
What Is an ICHRA and How Is It Different From a Group Plan or a QSEHRA?
An ICHRA is a type of health reimbursement arrangement created by a final rule the IRS, DOL, and HHS finalized in 2019, effective for plan years starting January 1, 2020. Instead of your company sponsoring a group medical plan through a carrier, you fund an account for each eligible employee. Employees buy an individual health insurance policy, either on the ACA marketplace (healthcare.gov or a state exchange) or off-exchange, and then submit proof of that coverage plus receipts or premium invoices to get reimbursed up to their allowance.
ICHRA vs. Traditional Group Health Plan
With a traditional group plan, you pick one or a handful of plan designs, negotiate rates with a carrier based on your group's claims history and size, and every enrolled employee gets the same network and benefit structure. With ICHRA, there's no group underwriting, no renewal shock tied to your specific claims experience, and no single plan design to manage. Your cost becomes predictable because you're setting a defined contribution rather than absorbing whatever the carrier decides your premium should be this year.
ICHRA vs. QSEHRA
People mix these two up constantly. A QSEHRA (Qualified Small Employer HRA) is only available to employers with fewer than 50 full-time equivalent employees that don't offer any group health plan, per IRS Notice 2017-67. QSEHRA also caps how much you can contribute. For 2025, the IRS capped QSEHRA reimbursements at $6,350 for self-only coverage and $12,800 for family coverage (IRS Revenue Procedure 2024-35). ICHRA has no employer size restriction and no dollar cap at all. A 500-person company can run an ICHRA. A 5-person company can too. That flexibility is the main reason ICHRA has become the more common choice for employers moving away from group coverage entirely.
Who Can You Actually Offer an ICHRA To?
This is where a lot of employers get tripped up, because ICHRA doesn't let you just pick favorites. The rules require you to offer the same ICHRA terms to everyone within a defined employee class, and the classes themselves come from a fixed list set by the 2019 final rule.
The 11 Employee Classes
Federal regulation allows employers to divide their workforce into these permissible classes for ICHRA purposes:
●Full-time employees
●Part-time employees
●Seasonal employees
●Employees covered by a collective bargaining agreement
●Employees in a waiting period before other coverage kicks in
●Foreign employees working abroad
●Salaried employees
●Non-salaried (hourly) employees
●Temporary employees placed by a staffing firm
●Employees in a geographic rating area (generally a state or a smaller area within a state)
●A combination of two or more of the above classes
Within a chosen class, you must offer the same ICHRA terms to everyone in it, though you can vary the dollar amount by age and family size using specific actuarial age-band rules. You can also carve out one class to keep on a traditional group plan while moving another class to ICHRA, which is a common transition strategy for employers who want to test the waters with, say, part-time staff before moving everyone.
Minimum Class Size Rules
If you're using classes to split your workforce between group coverage and ICHRA (rather than moving everyone to ICHRA at once), the final rule requires a minimum number of employees in the class getting ICHRA, to prevent employers from cherry-picking a handful of unhealthy or high-cost people into the group plan and pushing everyone else onto ICHRA. The minimum class size is 10 employees for employers with fewer than 100 employees, 10% of the workforce for employers with 100 to 200 employees, and 20 employees for employers over 200. These size rules don't apply if you're moving the entire company to ICHRA at once, which is the simpler path most small and mid-sized employers end up choosing.
How Much Should You Contribute, and Is It Affordable Under the ACA?
Setting Reimbursement Allowances
There's no IRS cap on how much you can put into an ICHRA. You could offer $50 a month or $1,500 a month. The real question isn't "how much can I contribute," it's "how much do I need to contribute" to satisfy your goals, which usually come down to two things: keeping employees whole compared to what they had before, and staying compliant with the ACA employer mandate if you're an applicable large employer (ALE) with 50 or more full-time equivalent employees.
The ACA Affordability Safe Harbors
If you're an ALE, offering an ICHRA can satisfy your employer mandate obligation under IRC Section 4980H, but only if the ICHRA is considered "affordable." Affordability is measured against a percentage of the employee's household income that the IRS updates every year. For plan year 2025, the IRS set that threshold at 9.02% of income (IRS Revenue Procedure 2024-35). For plan year 2026, the IRS moved that figure to 9.96% of income (IRS Revenue Procedure 2025-19), which actually gives employers a bit more room since a higher percentage threshold means you can contribute somewhat less and still clear the affordability bar. Because employers usually don't know an employee's exact household income, the IRS lets you use one of three safe harbors instead: the employee's W-2 wages, their rate of pay, or the federal poverty line. Most ICHRA administrators, including us at CafeHealth, run this affordability math automatically using the federal poverty line safe harbor since it's the simplest to apply consistently across your whole team.
One more piece that matters here: if your ICHRA offer is affordable and an employee turns it down anyway to buy a marketplace plan with a premium tax credit, they generally lose eligibility for that tax credit. If it's unaffordable, they can decline the ICHRA and still claim their subsidy. Getting this calculation right protects both the employee's wallet and your company from a potential IRS penalty letter down the road.
[Video]
What Does the Employee Experience Actually Look Like?
From the employee's side, the process is more hands-on than a traditional group plan, but it's not complicated once you walk through it once. Here's roughly how it goes:
1.They shop for a plan on healthcare.gov, a state exchange, or directly through an insurer, using their ICHRA allowance amount as a budget guide.
2.They enroll during open enrollment or, because losing employer group coverage and gaining ICHRA access triggers a special enrollment period, they can often enroll outside the usual window too.
3.They pay their own premium upfront, either directly to the carrier or, in some cases, through a premium payment integration your TPA sets up.
4.They submit proof of coverage and expenses to the ICHRA administrator, usually a copy of their insurance card, a premium bill, or an Explanation of Benefits for eligible medical costs.
5.They get reimbursed, tax-free, up to their monthly allowance, typically through direct deposit or payroll.
The learning curve is mostly about the shift in mindset. Employees who've had a company pick their plan for years suddenly have to compare deductibles and networks themselves. Good communication and a decent open enrollment support tool make a huge difference here. This is honestly the part where employers see the most pushback if they don't plan for it, so budgeting time for employee education isn't optional.
What Paperwork and Compliance Do You Need to Handle?
Notice Requirements
Federal ICHRA regulations require you to give employees a written notice at least 90 days before the start of the plan year the ICHRA applies to (or by the eligibility date for new hires who join mid-year). This notice has to spell out the allowance amount, which class the employee falls into, whether the ICHRA is expected to be affordable, and how it interacts with premium tax credits. HHS publishes a model notice you can adapt rather than draft from scratch.
Substantiation
Before any reimbursement goes out, you're required to substantiate that the employee actually has individual health coverage in force, and this has to be verified at least once a year plus for every new expense submitted. This isn't optional paperwork you can skip to speed things up. It's a core condition for the reimbursements to stay tax-free.
COBRA Interaction
If your company is subject to COBRA (generally 20 or more employees), an ICHRA counts as a group health plan and is subject to COBRA continuation rules just like a traditional plan, per DOL COBRA guidance. That means employees who lose ICHRA eligibility through a qualifying event, like termination, can elect to continue receiving their ICHRA allowance under COBRA for the standard 18-month period, paying the full cost themselves plus up to a 2% administrative fee.
ERISA and Plan Documents
An ICHRA is an ERISA welfare benefit plan, which means you need a formal plan document, a summary plan description, and Form 5500 filing if you're above the small-plan filing threshold. This is exactly the kind of administrative lift that trips up employers who try to run ICHRA in-house without support, which is why most companies hand this off to a TPA that specializes in it. Our ICHRA administration service handles the notices, substantiation, plan documents, and reimbursement processing so you're not managing spreadsheets and compliance deadlines on top of everything else you do.
How Do You Actually Switch From a Group Plan to ICHRA?
Employers who've done this well tend to follow a similar timeline. Here's what a realistic transition looks like:
●4 to 6 months out: Decide on employee classes and set contribution amounts. Model the cost against your current group plan spend so you know if you're saving money, breaking even, or increasing your budget to make coverage better for staff.
●90 days before the plan year starts: Send the required ICHRA notice to every eligible employee, along with plain-language education about what's changing and why.
●60 to 90 days before: Terminate or non-renew your group policy, coordinating the effective date with your carrier and broker so there's no coverage gap.
●Open enrollment window: Support employees as they shop for individual plans, ideally through a broker or enrollment tool that can walk them through marketplace options side by side.
●Plan year start: Begin processing substantiation and reimbursements. Expect the first month or two to generate the most questions as people get comfortable with the new process.
●Ongoing: Re-notice employees each year, update allowances for the new ACA affordability percentage, and file Form 5500 if required.
Brokers advising clients through this switch should flag one thing early: once you drop group coverage, you typically can't go back mid-year without a qualifying event, so this decision needs buy-in from leadership before you send that 90-day notice, not after.
If you're weighing whether ICHRA actually makes sense for your specific headcount, budget, and employee mix, that's a conversation worth having with someone who does this daily rather than guessing from a spreadsheet. Book a free consultation with Shannon and we'll walk through your numbers together, no pressure, just a clear answer on whether it fits.
Frequently Asked Questions
What is an ICHRA and how does it work?
It's a benefit where your company gives each employee a set monthly dollar amount instead of a group health plan. Employees buy their own individual insurance policy, submit proof of the coverage and their expenses, and get reimbursed tax-free up to whatever amount you set. You control the budget, they control the plan they pick.
Can a small business use ICHRA instead of a group health plan?
Yes, and this is actually one of the biggest draws. Unlike QSEHRA, which is capped at employers with under 50 full-time equivalent employees, ICHRA has no employer size limit at all. A five-person shop and a 500-person company can both run one, side by side with the exact same set of federal rules.
How much can an employer contribute to an ICHRA?
Whatever you decide. There's no IRS dollar cap on ICHRA contributions, unlike QSEHRA which caps out at $6,350 self-only and $12,800 family for 2025 (IRS Revenue Procedure 2024-35). The real limit isn't legal, it's practical: you need to contribute enough to be considered affordable if you're an applicable large employer trying to satisfy the ACA employer mandate.
Is ICHRA affordable under the ACA employer mandate?
It depends on how much you contribute relative to the employee's income. For 2025, affordability means the employee's net cost for the lowest-cost silver marketplace plan can't exceed 9.02% of income; for 2026, the IRS raised that threshold to 9.96Book a free chat with Shannon.